Can a Fourplex Really Let You Live for Free? Here Is How to Check the Math.
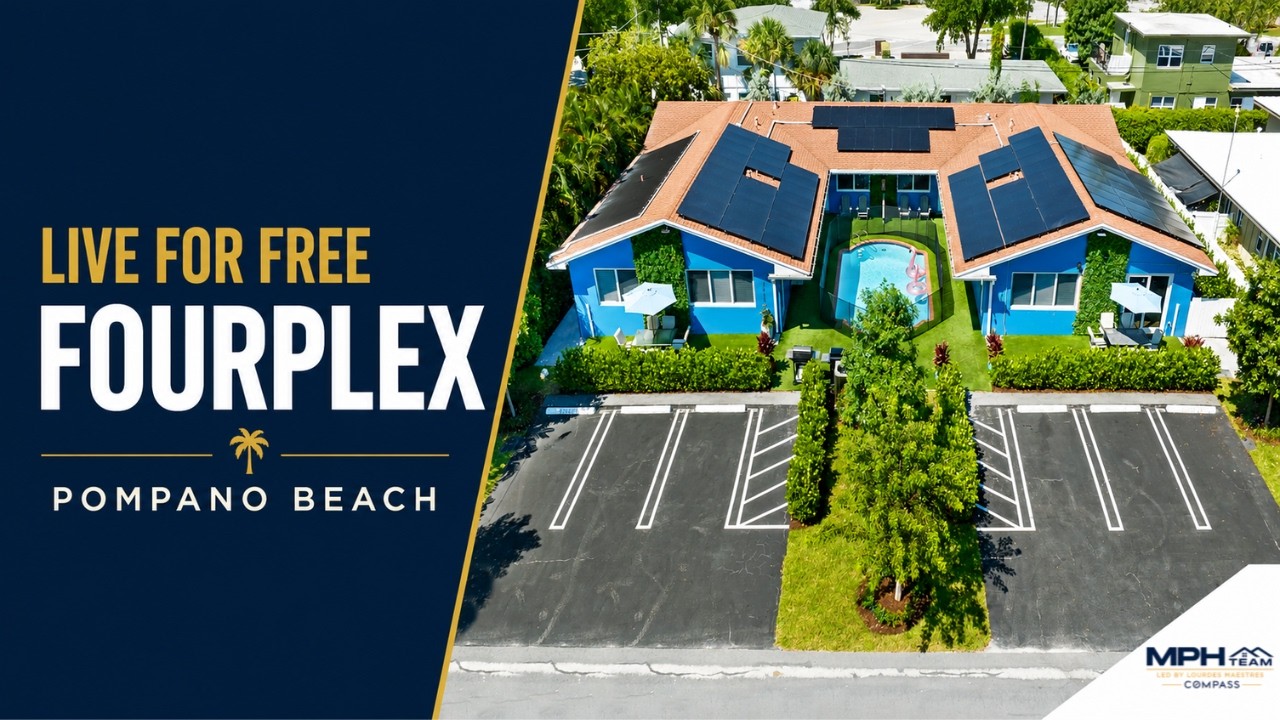
"Live for free" is one of the most oversold phrases in real estate, and occasionally it is literally true. On a renovated four-unit building we recently toured near the beach in Pompano, the idea is simple: you live in one unit and the other three carry the mortgage. Whether that actually works depends on the financing structure you choose, and the three options produce very different answers.
What house hacking actually means
You buy a small multi-unit building, occupy one unit, and rent the rest. Because you are living in it, you can access owner-occupant financing that a pure investor cannot. That single fact, not the rents, is usually what makes the math work. Investors on the same building are looking at a much larger down payment and a different rate, which is why the identical property can pencil for one buyer and not another.
Option one: FHA, low down, tighter monthly
FHA allows an owner-occupant to buy a two-to-four unit building with a small down payment. The tradeoff is a larger loan balance and mortgage insurance, so your monthly payment is high and the three rents have to work harder to cover it. This is the option for someone who has income but not much cash. It is not the option for someone who wants immediate cash flow.
Option two: conventional, more cash in, more breathing room
More money down means a smaller payment, and that is where three units covering the whole nut becomes realistic rather than aspirational. This is the version most buyers are actually picturing when they hear "live for free." Run it with a vacancy allowance and real reserves, not with all four units full for twelve straight months.
Option three: seller financing, the one people forget
When a seller is willing to carry paper, the terms are negotiable in ways a bank will never be. That flexibility can beat a lower headline price. It also comes with balloon dates and structure you need to read carefully, ideally with an attorney rather than with optimism.
The numbers to demand before you get excited
- Actual rent roll and lease end dates, not projected market rents
- A vacancy assumption you would be comfortable defending
- Insurance quote in writing, since South Florida insurance decides many of these deals
- Reserves for roof, systems, and the units you have not turned yet
- Short-term rental rules for that specific municipality, which vary block to block
- Your real down payment across all three financing paths, side by side
My honest take
House hacking works, and it works more often near the beach than people expect, but it works on paper first. Bring me a building you are considering, and we will run all three financing structures against the real rent roll before you write anything. If it only works in the optimistic version, I will tell you that.
Want the real read on your neighborhood?
Connect with the luxury real estate agent Fort Lauderdale homeowners rely on for honest, data-driven guidance.
Schedule a Consultation